$185K Broken Construction Loan, Redondo Beach | Hanover MC
By HanoverMC On September 14 2026
Hanover Mortgage Company arranged a $185,000 broken construction cash-out refinance in Redondo Beach, CA. See the deal terms.
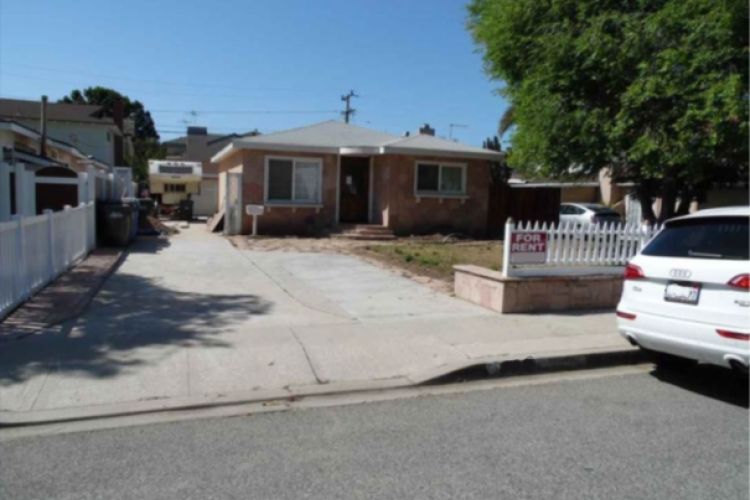
In Redondo Beach, a landlord sitting on an unencumbered property needed to move quickly — pulling cash for working capital and rehab costs on the duplex. Hanover Mortgage Company arranged the financing in first position, funded whole by a single private trust deed investor.
Call (714) 838-1474 x102 See more closed dealsThe borrower owned a duplex in Redondo Beach outright — no existing mortgage, no liens, full equity sitting untouched. The property itself wasn't the problem; access to that equity was. Rehab work was part of the picture, and the borrower wanted a cushion of working capital on hand rather than tying every dollar into the property.
A conventional bank refinance wasn't a fit at the time. Between the rehab scope and the property's near-term value not yet reflected in stabilized income, the file didn't line up well with conventional income and DTI underwriting. The borrower needed a path that could evaluate the deal on the asset and equity instead.
Hanover Mortgage Company underwrote the transaction against the property itself: title, location, unit condition, and the remaining rehab scope. With no existing mortgage to pay off, the file avoided one layer of complexity. It closed with lite documentation, evaluated organically as a whole file, and custom California loan documents were prepared for the funded-whole trust deed investor.
Construction on the property had stopped and restarted — what the industry calls broken construction — which put potential mechanic's liens tied to prior work into the title picture. That's a layer of complexity most lenders and banks have a harder time working through. Broken construction is a real niche, and Hanover Mortgage Company was meticulous in clearing that piece before closing.
Because the duplex is held as a rental property, the loan qualifies as business purpose financing. Hanover Mortgage Company looks at each file organically — the whole picture of the property, the borrower, and the deal — with lite documentation supporting that review rather than a narrow income or DTI checklist. It comes down to whether the loan makes sense as a whole, not any single number in isolation.
The loan closed at $185,000 in first position — roughly 19% of the property's value. It was structured on a 30-year amortization with a 7-year balloon, giving the borrower a manageable monthly payment now and years of runway to stabilize the units and plan a longer-term exit before the balloon comes due.
Discuss a similar scenarioThis note was funded whole — meaning a single private trust deed investor put up the entire $185,000, rather than the loan being split across several fractional investors. Practically, that tends to mean fewer moving parts at closing and less coordination needed on the capital side. Hanover Mortgage Company underwrote the transaction and arranged custom California loan documents; the capital itself came from that investor, consistent with how HanoverMC structures every deal it arranges.
Q: What does "broken construction" mean?
A: Broken construction refers to a property where building or renovation work started, then stopped before completion — often leaving behind unresolved contractor payments and potential mechanic's liens. It's a distinct niche in private lending because title and underwriting both require closer review than a standard purchase or refinance.
Q: Why would a free-and-clear property need private financing instead of a bank cash-out refinance?
A: Timing and underwriting fit. A bank refinance on a rental property still runs through income and DTI review, which doesn't line up well when a rehab budget is part of the picture. Business purpose private financing is evaluated on the asset and available equity instead.
Q: Why was the LTV only 19% on this deal?
A: The borrower only needed enough to cover working capital and rehab-related costs — not to maximize leverage against the property. Keeping the loan amount modest relative to the free-and-clear value kept the transaction simple.
Q: What does a 30-year amortization with a 7-year balloon mean for the borrower?
A: Payments are calculated as if the loan paid down over 30 years, which keeps the monthly payment manageable, but the full remaining balance comes due at year seven — time to stabilize the property before a longer-term refinance or sale. More on that in our article on balloon loan refinance options.
Q: Does "lite documentation" mean no documentation is required?
A: No. Lite documentation still requires some documentation — asset and title paperwork to support the file. Hanover Mortgage Company looks at each deal organically, evaluating the whole picture rather than following a fixed checklist.
Q: Can Hanover Mortgage Company arrange financing like this for other landlords?
A: Every deal is evaluated case by case. As general guidance, Hanover generally considers financing up to 70% LTV on 1–4 unit properties, with CLTV generally capped around 65%, though the equity position and use of funds drive the specifics of each transaction.
Call (714) 838-1474 x102 to discuss your scenario
Figures describe this specific, previously closed transaction only — not a quote or commitment to lend. Every borrower and property is underwritten on its own terms.
Hanover Mortgage Company arranges private, business-purpose mortgage financing for property owners and investors throughout California, evaluated on the asset and available equity rather than income or DTI. HanoverMC does not fund loans directly — capital comes from private trust deed investors, with financing arranged under HanoverMC's California DRE broker license.
DISCLAIMER
Hanover Mortgage Company is California licensed only. Real Estate Broker – California Department of Real Estate. Broker License #01410448 │ NMLS I.D. Number: 337458. INTEREST RATES CAN CHANGE WITHOUT NOTICE. ASK US FOR CURRENT RATE INFORMATION. BORROWERS AND PROPERTIES MUST QUALIFY. CONDITIONS AND RESTRICTIONS MAY APPLY. Loan programs, amounts, rates and terms are subject to change without notice. Loan approval is not guaranteed and all loan applications are subject to verification of acceptable credit, income, employment, lien position and value of collateral in the sole discretion of Hanover Mortgage Company. Flood and/or property hazard insurance may be required. Additional fees, conditions, restrictions and limitations may apply. Not all programs are available in all areas. The interest rate for adjustable rate mortgage loans is subject to increase. Please contact Hanover Mortgage Company to determine your eligibility for a specific loan product. Hanover Mortgage Company does not offer financing for those transactions defined as ‘Covered Loans’ or ‘High Cost Loans’ in any state or federal law. Hanover Mortgage Company is a Mortgage Broker. Mortgage Broker fees will apply unless stated otherwise. Disclosure: Money invested through a mortgage broker is not guaranteed to earn any interest or return and is not insured. State law dictates that we acknowledge that interest on trust deeds is not guaranteed. No investment is completely risk free and past performance is not a guarantee of future results. Before investing, investors must be provided applicable disclosure documents. Investment Products: Are Not FDIC Insured • Are Not Bank Guaranteed • May Lose Value • Are Not a Deposit • Are Not Insured by Any Federal Government Agency. Investments arranged through Hanover Mortgage Company are not insured or guaranteed. All investments carry inherent risks, including the potential loss of principal. Past performance is not indicative of future results.