Pre-HUD Mobile Home Refi on Land | HanoverMC
By HanoverMC On June 13 2024
Refinance a pre-1976 mobile home on owned land in California. Business-purpose, asset-based, lite doc. HanoverMC arranges loans case by case.
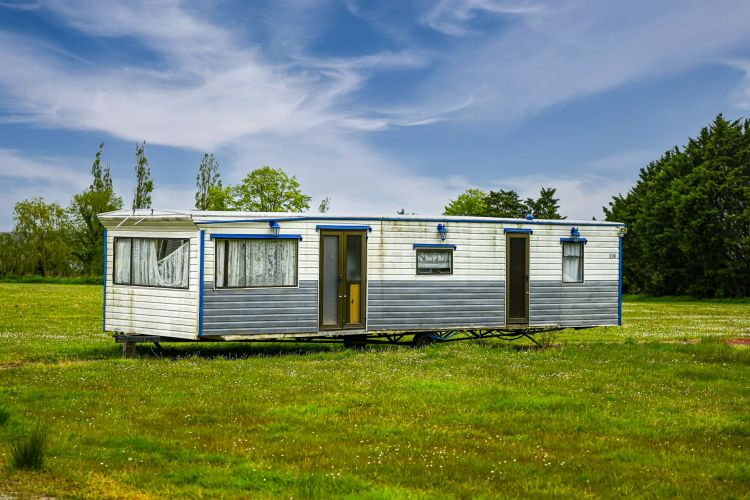
Manufactured homes built before June 15, 1976, the date the HUD Code took effect, sit in an awkward middle zone for most lenders. They are too old for conventional underwriting, often confused with mobile homes in parks, and easy to pass over without a closer look. For investors willing to do the diligence, that gap is where the opportunity is, especially when the home sits on land the owner holds outright rather than on a leased space in a mobile home park.
Owning the land changes the investment math. There's no lot rent, no park rules limiting resale, and no landlord who can decline to renew a ground lease. The land itself is real property collateral, a very different asset from a home with no land underneath it.
| Pre-HUD (before June 15, 1976) | HUD-Code (on or after June 15, 1976) | |
|---|---|---|
| Common name | Mobile home | Manufactured home |
| Built to | Pre-federal standards | Federal HUD Code |
| Conventional financing | Very limited | More widely available |
| Business-purpose refinance with land | Case by case | Case by case |
For an investor who has already renovated or stabilized a pre-HUD manufactured home on owned land, refinancing is often what makes the next deal possible. As the appraised value rises with renovation, the new equity can be accessed through a refinance and put to work, whether in the next purchase, further improvements to the same property, or better cash flow through improved terms. A cash-out refinance can also pay for updates to the home being refinanced, not only fund other projects.
This is where business-purpose financing differs from a typical homeowner refinance. The focus is on the property, its available equity, and the business purpose of the transaction, rather than the traditional consumer-mortgage underwriting model. That doesn't mean no documentation. Hanover Mortgage Company still requires lite documentation to underwrite the file and order customized California loan documents. It does not require the full income and employment file a conventional homeowner refinance would.
Not every dollar spent on a pre-HUD manufactured home returns the same value at appraisal. The improvements that tend to matter most:
Hire contractors with manufactured housing experience, not just site-built experience. The construction details differ, and the appraisal and underwriting will look closely at whether the work was done properly.
On larger parcels there may be room to add value beyond the existing home, such as an ADU, a junior ADU, or a second manufactured home, subject to local zoning and permits. The extra square footage can mean more rental income now and more equity to draw on in a future refinance.
Financing for pre-HUD manufactured homes is scarce in traditional mortgage lending, whether the home is owner-occupied or an investment. Private, asset-based financing is built for that gap.
Hanover Mortgage Company is a private money mortgage company that arranges business purpose 1st, 2nd, and 3rd lien loans for real estate investors throughout California, including refinances on pre-HUD manufactured homes with land. Hanover Mortgage Company does not fund loans directly. Private trust deed investors provide the capital, and Hanover Mortgage Company underwrites each file and orders custom California loan documents for every transaction. That structure allows flexibility on older or unusual properties that a bank might decline.
Have a pre-HUD manufactured home with land to refinance?
Submit Your Manufactured Home Scenario →This article covers business-purpose refinancing for pre-HUD manufactured homes with land. If your file is missing a foundation certification, see No 433A? You May Still Finance Your Manufactured Home in California. For other financing situations, browse the full Hanover Mortgage Company Blog.
Hanover Mortgage Company arranges private, business-purpose mortgage financing for property owners and investors throughout California, evaluated on the property and available equity rather than income or DTI. HanoverMC does not fund loans directly. Capital comes from private trust deed investors, and financing is arranged under HanoverMC's California DRE broker license.
Industry trends, real estate news, and loan closings — straight to your inbox.
Subscribe to our newsletterBy subscribing you agree to our Privacy Policy and Terms of Service.
DISCLAIMER
Hanover Mortgage Company is California licensed only. Real Estate Broker – California Department of Real Estate. Broker License #01410448 │ NMLS I.D. Number: 337458. INTEREST RATES CAN CHANGE WITHOUT NOTICE. ASK US FOR CURRENT RATE INFORMATION. BORROWERS AND PROPERTIES MUST QUALIFY. CONDITIONS AND RESTRICTIONS MAY APPLY. Loan programs, amounts, rates and terms are subject to change without notice. Loan approval is not guaranteed and all loan applications are subject to verification of acceptable credit, income, employment, lien position and value of collateral in the sole discretion of Hanover Mortgage Company. Flood and/or property hazard insurance may be required. Additional fees, conditions, restrictions and limitations may apply. Not all programs are available in all areas. The interest rate for adjustable rate mortgage loans is subject to increase. Please contact Hanover Mortgage Company to determine your eligibility for a specific loan product. Hanover Mortgage Company does not offer financing for those transactions defined as ‘Covered Loans’ or ‘High Cost Loans’ in any state or federal law. Hanover Mortgage Company is a Mortgage Broker. Mortgage Broker fees will apply unless stated otherwise. Disclosure: Money invested through a mortgage broker is not guaranteed to earn any interest or return and is not insured. State law dictates that we acknowledge that interest on trust deeds is not guaranteed. No investment is completely risk free and past performance is not a guarantee of future results. Before investing, investors must be provided applicable disclosure documents. Investment Products: Are Not FDIC Insured • Are Not Bank Guaranteed • May Lose Value • Are Not a Deposit • Are Not Insured by Any Federal Government Agency. Investments arranged through Hanover Mortgage Company are not insured or guaranteed. All investments carry inherent risks, including the potential loss of principal. Past performance is not indicative of future results.
